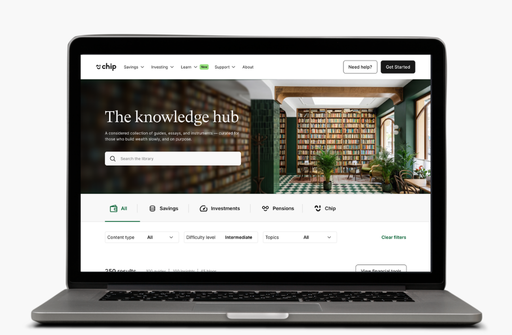
The knowledge hub

A considered collection of guides, essays, and instruments — curated for those who build wealth slowly, and on purpose.

0
results
Filter results
Filter by:
Content type
Difficulty level
Topics
0
results
View financial tools
Understanding Self-Invested Personal Pensions (SIPPs)
2 min read
Intermediate
Pension basics

What is a SIPP?  

A SIPP is a private pension ‘wrapper’ that gives you flexibility over both your investments choices and how you manage old pensions. With a SIPP, you can:

  • Consolidate: Combine old workplace pensions that you no longer contribute to and may not be working for you into a single account. Read our full guide on pension consolidation.‍
  • Invest with control: Get full visibility and control over your investments within your pension.

‍

How does a SIPP work?  

A SIPP works in a similar way to other defined contribution pensions, but with added flexibility and often a wider range of investment choices. It functions like a tax-efficient retirement savings account. You contribute, and the government tops your contributions up with tax relief.

  • Tax relief bonus: If you pay in £80, the government adds £20 in basic-rate tax relief to make your total contribution to£100. Higher and additional rate taxpayers can claim extra relief.
  • Investments: Your contributions are then invested into your chosen assets with the aim of growing your money.‍
  • Tax-efficient growth: As long as investments are held inside the SIPP, you pay no Capital Gains Tax or Income tax on any growth generated in the pension.

‍

How to set up a SIPP  

Setting up a SIPP is simple:

  1. Choose a provider: Look for a provider that offers clear fees and an investment offering that’s right for your retirement goals and level of experience.
  2. Fund your account: You can transfer your old pensions, set up monthly recurring contributions, or pay in a lump sum.‍
  3. Stick to your strategy: Choose investments that align with your goals and risk appetite. Some SIPPs require you to choose individual stocks, while many also offer ready-made solutions such as Target Date Funds. These funds automatically shift from higher risk to lower risk investments as you approach retirement.

‍

Can I have a SIPP and a workplace pension? 

Yes, you can have both at the same time. A common strategy used is to keep current workplace pensions to benefit from employer's contributions, but use a SIPP to consolidate all previous workplace pensions that are no longer being paid into.

Having a SIPP with those old pensions generally makes it easier to keep track of where each old pot is and more control on how it is invested

Read our full guide on workplace pensions.

‍

How many SIPPs can I have? 

Savers are not limited by the number of SIPPs they can hold. However, some people find it easier to keep everything in one place. Having a single SIPP can make it easier to get a better picture of retirement wealth and can often reduce the fees paid.

‍

How much can I pay into a SIPP? 

The two main limits you need to be aware of when paying into a SIPP are:

  • The earnings limit: You can usually only receive tax relief on personal contributions up to 100% of your relevant UK earnings each tax year. For example, if you earn £30,000, you cannot personally contribute more than £30,000 and still receive tax relief
  • The annual allowance: There is also a total cap of £60,000 per tax year (or 100% of your earnings, whichever is lower). This allowance includes all contributions - from you, your employer, and the government’s tax relief. 

Read our full guide on pensions tax, relief and allowances.

‍

What age can I draw my private pension? 

The trade-off for the tax benefits of a SIPP is that your money is locked away until a set minimum age.

  • Currently you can access your SIPP from age 55.
  • From 2028 this will rise to age 57.

Once you reach this age you’ll have the options to:

  • take 25% of the pot as a tax-free lump sum, 
  • buy an annuity (guaranteed income plan), or;
  • leave the rest invested and withdraw the cash as you need (drawdown).

We’ll come back to each of these three scenarios later. 

Read our full guide on retirement ages.

‍

The State Pension

Whilst your workplace pension and SIPP help serve as your tools for building your personal retirement pot, you may also be entitled to the State Pension, provided you meet the qualifying criteria. This serves as a guaranteed foundation to your retirement income, with the amount you receive based on your National Insurance record. 

In the next guide we’ll cover how the State Pension system works, and what you can expect to receive if you qualify.

Biggest companies in the UK by market cap
2 min read
Beginner
Global cap giants

What are the biggest companies in the UK by market cap?

This list ranks the UK’s biggest public companies by market capitalisation; the cumulative value of a company's total outstanding market shares. We’ll also be highlighting other key figures, such as the company's revenue, gross profit, and 1-year return (all based on the previous fiscal year). 

Some other key facts such as the exchange the company is listed on, the founding year and country the company is headquartered in are also covered.

‍

1. AstraZeneca PLC

  • Market cap: £182.77 billion
  • Revenue: £43.67 billion
  • Gross profit: £31.67 billion
  • 1-yr return: - 10.57%
  • Exchange: London Stock Exchange
  • Year founded: 1913
  • Country: United Kingdom

AstraZeneca is a global, science-led biopharmaceutical company that focuses on the discovery, development, and commercialisation of prescription medicines.

  • Pharmaceuticals: A leading developer of treatments in major disease areas.
  • Global reach: Its innovative medicines are used by millions of patients worldwide.

‍

2. HSBC Holdings PLC

  • Market cap: £164.23 billion
  • Revenue: £110.12 billion
  • Gross profit: N/A 
  • 1-yr return: + 42.14%
  • Exchange: London Stock Exchange
  • Year founded: 1959
  • Country: United Kingdom

HSBC is one of the world’s largest banking and financial services organisations, serving customers worldwide from offices in 62 countries and territories.

  • Wealth and personal banking: Provides a range of services from current accounts and mortgages to wealth management and insurance for individuals.
  • Commercial banking: Offers banking services to small, medium-sized, and large corporations.
  • Global banking and markets: Provides financial services and products to corporate, government, and institutional clients.

‍

3. Shell PLC

  • Market cap: £158.58 billion
  • Revenue: £212.38 billion
  • Gross profit: £36.13 billion
  • 1-yr return: - 0.33%
  • Exchange: London Stock Exchange
  • Year founded: 2002
  • Country: United Kingdom

Shell is a global group of energy and petrochemical companies with a focus on the entire energy value chain.

  • Integrated gas and upstream: Explores for and extracts crude oil, natural gas, and natural gas liquids. It also markets and transports oil and gas.
  • Downstream and renewables: Turns crude oil into a range of refined products, which are moved and marketed around the world for domestic, industrial, and transport use. It is also investing heavily in low-carbon energy solutions like biofuels, hydrogen, and wind power.

‍

4. Unilever PLC

  • Market cap: £114.06 billion
  • Revenue: £50.24 billion
  • Gross profit: N/A
  • 1-yr return: - 5.63%
  • Exchange: London Stock Exchange
  • Year founded: 1930
  • Country: United Kingdom

Unilever is one of the world's leading suppliers of Beauty & Wellbeing, Personal Care, Home Care, and Nutrition products with sales in over 190 countries.

  • Global brands: Owns over 400 brands, including Dove, Ben & Jerry's, Knorr, Lipton, Magnum, and Persil.
  • Consumer reach: Its products are used by 3.4 billion people every day.

‍

5. British American Tobacco PLC

  • Market cap: £91.37 billion
  • Revenue: £25.6 billion
  • Gross profit: £16.58 billion
  • 1-yr return: + 46.86%
  • Exchange: London Stock Exchange
  • Year founded: 1902
  • Country: United Kingdom

British American Tobacco (BAT) is a leading, multi-category consumer goods business that provides tobacco and nicotine products to millions of consumers around the world.

  • Traditional tobacco: A leading global seller of cigarettes with brands like Dunhill, Kent, and Lucky Strike.
  • New categories: Investing heavily in a portfolio of non-combustible products, including vapour (Vuse), heated tobacco (glo), and modern oral nicotine pouches (Velo).

‍

6. Rolls Royce Holdings 

  • Market cap: £90.23 billion
  • Revenue: £19.54 billion
  • Gross profit: £4.77 billion
  • 1-yr return: + 119.47%
  • Exchange: London Stock Exchange
  • Year founded: 1906
  • Country: United Kingdom

A world-leading industrial technology company that provides complex power and propulsion solutions for critical applications.

  • Civil aerospace: Designs and manufactures engines for large commercial aircraft like the Airbus A350 and Boeing 787.
  • Defence: A key supplier of engines for military aircraft and naval vessels worldwide.

‍

7. Rio Tinto PLC

  • Market cap: £78.93 billion
  • Revenue: £41.53 billion
  • Gross profit: £10.08 billion
  • 1-yr return: - 4.47%
  • Exchange: London Stock Exchange
  • Year founded: 1873
  • Country: United Kingdom

Rio Tinto is a leading global mining group that focuses on finding, mining, and processing mineral resources.

  • Key materials: A major producer of iron ore for steel, aluminium for cars and smartphones, copper for wind turbines, and other essential minerals.
  • Global operations: Owns and operates open pit and underground mines, mills, refineries, and smelters, as well as a network of railways and ports.

‍

8. BP PLC

  • Market cap: £66.81 billion
  • Revenue: £144.2 billion
  • Gross profit: £22.79 billion
  • 1-yr return: - 1.11%
  • Exchange: London Stock Exchange
  • Year founded: 1908
  • Country: United Kingdom

BP is a global integrated energy company that delivers solutions for heat, light, and mobility.

  • Oil and gas: Focuses on exploration, production, and refining of oil and natural gas.
  • Convenience & mobility: Operates a large network of retail service stations.
  • Low carbon energy: Investing in renewable energy sources, including bioenergy, hydrogen, and wind and solar power, as part of its transition to a net-zero company.

‍

9. RELX PLC

  • Market cap: £62.96 billion
  • Revenue: £9.53 billion
  • Gross profit: £5.99 billion
  • 1-yr return: - 4.01%
  • Exchange: London Stock Exchange
  • Year founded: 1903‍
  • Country: United Kingdom

A global provider of information-based analytics and decision tools for professional and business customers.

  • Risk: Provides data and tools for evaluating risk for industries like insurance and banking.
  • Scientific, technical & medical: A major academic publisher through its Elsevier division.

‍

10. GSK PLC

  • Market cap: £58.51 billion
  • Revenue: £31.63 billion
  • Gross profit: £22.68 billion
  • 1-yr return: + 13.88%
  • Exchange: London Stock Exchange
  • Year founded: 1715‍
  • Country: United Kingdom

GSK (formerly GlaxoSmithKline) is a global biopharma company with a focus on uniting science, technology, and talent to get ahead of disease together.

  • Vaccines: A world-leading vaccine business, providing protection against a range of infectious diseases.
  • Specialty medicines: Develops and manufactures innovative medicines for areas such as HIV, respiratory diseases, and immunology.

‍

What are the biggest companies by total annual revenue?

  • Shell: £214.24 billion
  • Glencore: £180.76 billion
  • BP: £148.05 billion
  • HSBC: £116.6 billion
  • Tesco: £69.92 billion

‍

What are the biggest companies by workforce?

  • Tesco: 336,430
  • HSBC: 211,000
  • Glencore: 150,000
  • Unilever: 120,040

‍

Summary

Understanding a company's performance is crucial; it's how you truly know what you own. These metrics directly drive the value of your stocks and funds. When you understand these key drivers, you can navigate market changes with confidence, rather than just reacting to headlines.

Next we’ll be looking at the biggest companies in Europe by market cap.

All market data sourced from TradingView and company reports as of 01.09.2025.

Moonshot capitalism: AI rewrites the venture capital playbook

2 min read

The AI boom is fuelling a resurgence in ambitious “moonshot” bets, as early SpaceX backers’ huge returns and falling valuations for traditional software companies force tech investors to embrace riskier and more capital-intensive dealmaking.

Ideas once considered outlandish, from nuclear fusion to melding humans with machines, are gaining attention from venture capital firms that even a few years ago would never have touched start-ups in such sectors.

“The world definitely has changed,” said Matt Robinson, partner at VC firm Accel. “Look inside any VC’s office and the kind of companies they are discussing over the last couple of years has transformed.”

Excluding the giant sums ploughed into AI start-ups, global investment in “deep tech” — companies whose products are rooted in big scientific or engineering advances — has exceeded $150bn since the start of 2024, more than the $133bn in the entire decade to the end of 2019, according to Dealroom.

Ambitious founders in Silicon Valley are cheering a return to greater risk-taking from investors, after an extended stretch following the dotcom bust in which VCs became preoccupied with backing predictable enterprise software companies.

‍

“The most profitable [start-ups] to invest in were all software businesses on the internet for a period of time, when the internet was new and growing,” said Max Hodak, co-founder of Science, a brain-computer interface start-up. “That sucked a lot of oxygen out of physical hardware because it’s harder . . . Was that totally healthy? Probably not — but we’re back.” 

Hodak, who also co-founded Neuralink alongside Elon Musk, argues that VCs’ interest in software was itself a “detour” from the hardware ventures that helped Silicon Valley emerge decades ago. 

“The original ‘OG’ venture capital built the railroads. This is really the magic of capitalism,” he said. 

This year’s deep-tech investments have not yet surpassed 2021’s peak, which was propelled by battery and electric vehicle deals for the likes of Rivian and Northvolt — many of which turned sour, highlighting the risks involved in moonshot dealmaking.  

But the extraordinary volumes of capital flowing into AI model companies are spurring a rise in bets that could revolutionise how data centres are powered or even put them into space, as well as reviving interest in other science-fiction ideas that AI promises to bring closer to reality.

“There is a feeling of turning the oil tanker,” said one VC executive specialising in “frontier” tech of the sense among investors that they have to move beyond software-as-a-service.

“But it’s such a different thing to underwrite a quantum computing company to something where you’ve had such a strong set of benchmarks that you could put in a spreadsheet.”  The AI infrastructure boom in particular has created new markets and customers for all kinds of wild ideas.

“Today there is almost a ‘why now’ for everything,” Robinson said. “You used to be able to say, this one goes in the too-hard bucket. And I don’t think you have that option any more.”

AI-powered simulations are already slashing the cost of experimenting in areas such as fusion and space tech, lowering the upfront spending requirements that have traditionally been associated with hardware ventures. 

AI is “really transforming what you can do ‘in silico’ before you do it in the physical world,” said Carina Namih, investor at London-based VC Plural. “That is driving a massive acceleration in those deep-tech fields. So the capital intensity to get those returns has really changed.”

But the timeline to cashing in those returns remains uncertain. Raising capital for moonshot ideas may be getting easier but the path to commercialisation is often just as hard as the initial tech breakthrough. 

Alphabet’s X lab popularised the idea of moonshot investments more than a decade ago, when Google’s parent company created an incubator for long-shot ideas that traditional investors rarely backed. It has produced both hits — such as Waymo, the self-driving car venture now valued at $126bn — and misses including Loon, which had hoped to deliver internet access to remote areas via high-altitude balloons before it was shuttered in 2021. 

But even Google’s starry-eyed approach to innovation is now becoming more grounded. In a recent interview with Fast Company, Alphabet’s “captain of moonshots” Astro Teller said X now spent more time studying the business case and technical feasibility of its latest ideas, which include Bellwether, an AI-driven forecasting system aimed at predicting natural disasters. 

Moonshot investors concede there is no traditional valuation metric that can win over an investment committee when it comes to ideas like putting data centres or biology labs in space. Writing a speculative cheque is often the only way to see which science project might turn into the next SpaceX.

Some of this year’s biggest deep-tech deals outside of AI include space start-ups Sierra Space, Axiom Space and Iceye, as well as fusion start-ups Helion, Proxima and Inertia. 

“One of the things everyone considered very difficult about the space industry, until now, was there was a very high barrier to entry,” said Ariel Ekblaw, chief executive of space architecture R&D lab the Aurelia Institute and an investor in space tech, noting that in the AI era, “entire products . . . can be rebuilt in a day”. 

The wealth created by the SpaceX IPO is fuelling a fear of missing out among “people who did not get invested in that first wave”, Ekblaw added, predicting this would spark a “Cambrian explosion of new start-ups” targeting the space industry. Founders Fund, for example, turned a roughly $600mn investment in Musk’s rocket, satellite and AI group into a stake worth more than $50bn at the company’s initial public offering, according to PitchBook estimates. 

Ekblaw predicts that falling launch costs will unlock new applications for the space industry, from energy to in-space manufacturing. 

“There is a real need for more orchestration of solar power in orbit between space assets that enables high-power activities . . . that were not happening before,” she said. “The corollary to that is space-to-ground, which is profoundly more efficient green energy and you can do it even at night.” 

Start-ups such as Overview Energy and Reflect Orbital are planning to float giant mirrors in orbit that would reflect sunlight back to Earth, while Florida-based Star Catcher raised $65mn in May to build a power grid in space using “optical power beaming”. 

“We are going to see a maturation of the space industry, like we did with commercial aviation,” said Ekblaw. “We are in the early stages of that transition.” 

Bouncing sunlight around in orbit might seem like less of a daunting investment prospect for portfolio managers whose software stocks have been hammered by this year’s “SaaSpocalypse”, which wiped away hundreds of billions of dollars in market value. Some of those losses were recouped after last month’s earnings reports from the likes of Salesforce.com showed a potential uplift from AI.

AI model companies such as Anthropic could end up swallowing much of the market served by today’s traditional software companies, according to Bejul Somaia, partner at Lightspeed Venture Partners.

“On the applications side, one of the biggest and most difficult things to underwrite right now in software-only businesses is durability and differentiation,” he said. “Where will the models end?” 

As AI threatens to destroy many of the “moats” that traditional software incumbents have relied on to protect their businesses, many tech investors now argue that venture capital must also reinvent itself for a new, less certain era in the tech industry. 

“In category after category, the terminal value we once counted on no longer holds,” Hemant Taneja, who heads VC firm General Catalyst, wrote in an essay in July. “For an outcome to matter now, founders must build far bigger companies than before.”

Hodak, who is preparing to bring to market Science’s first product — a retinal implant that can restore sight — bristles at the “moonshot” label. 

“Just because it’s a big ambitious goal, I don’t think it needs, in the psyche of the popular imagination, to mean it’s unlikely,” he said.

“The original moonshot worked. We did in fact leave a flag on the moon.” 
‍

‍

The U.S. Government has ‘gone fishing’ (but don't worry)
2 min read
Expert
Economic context

A US government shutdown* has been triggered after a deadline to reach a funding agreement before the start of the new fiscal year (1 October) came and went without a deal.

Noisy headlines like these can feel unsettling, but history shows that markets usually take them in stride. While shutdowns can cause short-term noise, they rarely derail the bigger picture for long-term investors.¹

‍Chip explains: What is a government shutdown?: In the U.S., Congress has to approve funding for government operations. If lawmakers can’t agree on a budget before the 1 October deadline, parts of the government temporarily close until a deal is reached.‍

‍

What might happen in the short term?

  • Data delays: Key economic reports could be postponed, creating a temporary “blind spot” for analysts and traders.
  • Government-linked sectors: Contractors and defence companies may face small payment lags, but these tend to be resolved once funding resumes.
  • Market sentiment: Expect some short-term jitters and reactive headlines in the news cycle, but past shutdowns haven’t caused lasting damage.

‍

Why investors don’t need to panic

The most important thing to note is that history is on your side. U.S. markets have been largely unaffected by previous shutdowns, with long-term returns back on track once political gridlock passes.2

Diversification also plays an important role. By spreading your money across different regions, sectors, and asset classes, you avoid being overly exposed to temporary political standoffs like this.

And most importantly, while headlines can spark short-term nerves, it’s worth remembering that the bigger picture matters far more than these short-lived disputes, so stick to the plan.  
‍

How Chip helps you stay steady

At Chip, we keep investing simple and diversified. Choose from over 40 investment funds – offering clear, curated choices without overwhelming you with thousands of options.

If you’re investing for the long term, the message is clear. Stay the course, let diversification do its job, and keep your goals in focus.

Head to the ‘Invest’ tab in your Chip app and see how you could put your money to work today with a tax-free Stocks & Shares ISA or General Investment Account.

‍

Sources:

1 JP Morgan

2 Voya

Bringing stories from the FT into Chip‍
2 min read

We’re delighted to give Chip members free access to a curated selection of insightful articles from the Financial Times (commonly abbreviated to the FT). 

These articles will only be available to read in the Chip app, making this an exclusive benefit to our members. 

They’ll be refreshed every week with new relevant articles being added as the markets and news cycle moves. 

We’ll be slowly rolling this out over the coming weeks, so keep your eyes open for the first articles appearing in your app. 

‍

World-class financial journalism in Chip

The FT has a strong reputation for writing world-class financial content stretching back over 100 years.

They’re widely recognised as one of the world’s most influential financial newspapers, with hundreds of journalists, editors and experts generating fact-checked content, covering everything the economy touches. 

So in short, we feel we’re bringing our members the very best financial content we can find. 

‍

Bringing valuable insight to Chip members 

As much as we're giving our members free access to a selection of the FT’s content (which is usually behind a paywall) for their enjoyment, this is to help them make informed decisions. 

Ultimately we want to give our members access to the insight and knowledge needed to make wise choices about their wealth and investments, by leveraging the expert insight and analysis from the FT’s team. 

So with this in mind, rather than simply bringing you breaking news from the FT, we’ll be focusing on:

  • Opinion pieces
  • Long reads covering economic trends 
  • Market insights and breaking news
  • Personal finance and lifestyle stories

We hope this can help you build an informed picture about what to do with your wealth by serving a balanced mix of thought-provoking topics on the economy and markets as explained by experts.

But as we always say, we’re building Chip for you, with you. So, don’t hesitate to get in touch if you have any thoughts about articles we should add. 

‍

Putting editorial content at the heart of Chip

The FT content is going to be just one part of reimagining our investment product. 

You’ll notice the investments tab adding increasing amounts of editorial content and insight that better explain what the available investments are, where they fit in your portfolio, and what’s in them. 

‍

Just note, your capital is at risk when you invest.

‍

Reasons to be bullish on equities

2 min read
Source: Michael Nagle/Bloomberg

‍

The writer is chief multi-asset strategist at HSBC.

Given the scale of negative developments that markets have had to contend with in the last five years — from a pandemic to energy shocks — it seems nothing short of breathtaking that riskier assets like equities have been so resilient.

One popular narrative is that this has recently been a result of AI, which is seen as the sole driver of current strong earnings growth in the US. But that belies the broader trend.

Even outside of tech and AI, US earnings are currently about 50 per cent above the pre-Covid trend. Higher nominal economic growth and multi-decade low corporate tax rates have been major drivers behind this. And outside the US, earnings growth has been rising in the last 12 to 18 months.

From a top-down perspective too, there is a gap between current conditions in the economy and the consensus view which has persistently run counter to the popular adage of “never bet against the US consumer” in the past few years. As a result, the US economy has repeatedly surprised on the upside.And there’s a long list of other reasons behind the strength of equity markets.

Increased allocations to equities: Higher inflation since 2021 has spurred a shift in equity-bond market correlations, with the asset classes moving more in tune with each other. Bonds no longer diversify portfolios as they used to, let alone hedge them.

We think this means allocations to equities will probably remain high in the coming quarters, with big investors seeking downside protection via option markets and other more exotic strategies. These allocations support not just higher valuations of equities but also the spectrum of riskier assets.

The wealth effect: The increase in US household wealth has been much more rapid than pre-Covid. This isn’t just a function of higher equity markets. Even the value of cash holdings is almost 50 per cent above trend.

The vast majority of this increase in US wealth is among high-income households — those that not only spend the most but also invest a bigger portion of their wealth back in financial markets.Larger central bank toolkit.

Analogies between current conditions and the lead-up to the 2007-08 financial crisis are often made. What those comparisons miss is that central banks have a much wider toolkit nowadays — and they aren’t afraid of inventing new ones if need be, even in the middle of a rate-rising cycle.

The Federal Reserve’s emergency liquidity programme in 2023 was one example of this. Such implied support boosts risk appetite.Lower oil intensity of developed economies. Compared with the 1970s and 1980s, consumer spending on energy as well as economy-wide energy consumption per GDP is much lower nowadays.

This means that, even as shocks such as Russia-Ukraine or the Middle East conflict have led to higher oil prices, riskier assets have largely taken them in their stride.Low private sector leverage and lower sensitivity to interest rates.

The US housing market remains in the doldrums and interest rates have risen. But the average effective rate on existing mortgages is actually some 2 percentage points lower than the current rates being offered. And housing activity is no longer as important as it was before the financial crisis.

Lower interest rate sensitivity also applies to consumers and corporates overall: the ratio of US household debt payments to disposable income, for example, is not even at the average levels seen in the 2010s, let alone the levels before the financial crisis.

For companies, net interest payments have slumped to a more than 20-year low and to record lows when compared with record-high corporate profits. And almost two-thirds of bonds and loans of S&P 500 companies won’t expire until after 2030, with only about 10 per cent of debt being on a floating rate these days.

Quicker information flow and price discovery and other technical factors.

Programme trading, AI, social media etc have all contributed to a quicker information flow. Drawdowns now happen much quicker. But so do recoveries, in turn fuelling the buy-the-dip mentality further.

Other technical factors include the rise of index investing. Buying and selling linked to the rebalancing of index fund vehicles can dampen stock market volatility.

As ever, there are risks to the bullish view and we may well see short-term drawdowns in riskier assets in future. But the list of structurally supportive factors is simply too long for me to join the bearish camp.

Passive and active investing explained
2 min read
Beginner
Investing strategies

What is passive investing?

Passive investing is a long-term investment strategy that aims to replicate the performance of a market index, rather than trying to beat it.

Investors typically buy into funds, such as index funds or exchange-traded funds (ETFs), that track a broad market benchmark like the FTSE 100 or S&P 500.

Key passive investing characteristics
  • Low cost: Passive funds generally have lower fees because they require minimal management. 
  • Buy-and-hold approach: Passive investors aim to ride out market ups and downs over time. 
  • Diversification: Tracking an index provides exposure to a wide range of companies.

‍

What is active investing?

Active investing involves ongoing decision-making to buy, hold, or sell assets in an attempt to outperform the market. 

This strategy is often managed by fund managers or individual investors who analyse market trends, company performance, and economic indicators to make investment choices.

Key active investing characteristics
  • Higher costs: Fund management, research, and transaction fees tend to be higher. Learn about investment fees and costs.‍
  • Tactical decisions: Active managers may buy or sell holdings frequently to exploit market opportunities.
  • Potential for higher returns: Success depends on skill, timing, and market conditions.

‍

The advantages and disadvantages of passive investing

Advantages of passive investing include:
  • Lower fees: Less management means reduced ongoing costs.
  • Simplicity: Ideal for beginners; less time and knowledge required.
  • Market-matching performance: Often performs better than many actively managed funds over the long term.
Disadvantages of passive investing include:
  • No chance to outperform the market: Returns will always closely mirror the index.
  • Limited flexibility: Can’t adjust quickly to market shifts or exploit short-term opportunities.
  • Market downturns: Passive funds track indexes even during declines, with no defensive measures in place.

‍

The advantages and disadvantages of active investing

Advantages of active investing include:
  • Opportunity for higher returns: Skilled asset managers can outperform the market, especially in less efficient markets.
  • Flexibility: Managers can pivot strategies in response to changing conditions.
  • Tailored investment strategies: Portfolios can be aligned with specific goals or themes (e.g., ethical investing, emerging markets).
Disadvantages of active investing include:
  • Higher costs: Active funds charge more, which can eat into returns.
  • Greater risk of underperformance: Many active funds fail to beat their benchmarks after fees.
  • Requires more research and monitoring: Not ideal for novice investors or those short on time.

‍

Is active or passive investing right for me?

Choosing between active and passive investing depends on your goals, how much time you want to dedicate to managing your investments, and how comfortable you are with risk. How to know your risk tolerance.

If you're just starting out, passive investing is often a practical and beginner-friendly option. It requires little ongoing effort, keeps costs low, and provides broad exposure to the market.

It’s especially suited to long-term investors who prefer a “set it and forget it” approach and are happy with market-average returns.

On the other hand, if you're someone who enjoys researching companies, keeping up with economic trends, and believes in your ability (or that of a professional) to spot investment opportunities, active investing might appeal to you. 

It offers the potential for higher returns but comes with more risk, higher fees, and a greater time commitment.

You should also consider your risk tolerance. Passive investing tends to be more stable and predictable, while active investing can be more volatile, especially over shorter periods.

Importantly, you don’t have to choose one or the other. Many investors find that a blend of both, using passive strategies for long-term stability and active ones for targeted opportunities, gives them the best of both worlds.

‍

How to combine active and passive investing

Many investors choose a blended approach, combining both active and passive strategies to balance cost, control, and opportunity.

Common combinations:

  • Core and satellite: Use a passive fund for the core of your portfolio, with smaller “satellite” allocations to active funds targeting specific sectors or regions.
  • Thematic investing: Stick with passive index funds for broad market exposure and add active investments in areas you believe have strong growth potential.
  • Rebalancing over time: Start passive, then explore active strategies as your confidence and knowledge grow.

This approach allows flexibility while keeping fees manageable and risk diversified.

‍

Passive and active investing summary

Understanding the core differences between passive and active investing is essential for building a strategy that suits your financial goals and comfort level. 

While passive investing offers cost-efficiency and simplicity, active investing presents opportunities for higher returns, albeit with added risk and effort.

Ultimately, there's no one-size-fits-all answer. Many UK investors successfully use a mix of both approaches to suit their needs.

In the next guide in our Investment Strategies series, we’ll explore another foundational concept: Growth Investing vs Value Investing, two popular approaches to selecting individual stocks.

‍

Interest rates and the stock market
2 min read
Intermediate
Economic context

What are interest rates?

Interest rates are basically the price of borrowing money, or the reward you get for saving it. In the UK, the Bank of England sets something called the base rate, which influences how much banks charge on loans or pay on savings.

For example, if the base rate is 5%, your bank might offer a mortgage at 6% or a savings account at 4%. When rates go up, borrowing gets more expensive, but saving becomes more rewarding.

‍

Why do central banks change the interest rate?

Central banks, such as the Bank of England (UK), Federal Reserve (US) and European Central Bank (EU), adjust interest rates to keep inflation under control. They do this to try and maintain economic stability. 

  • If inflation is rising too fast, rates are increased to cool spending.
  • If the economy is slowing, rates are lowered to encourage borrowing and investment.

The goal is to strike a balance by encouraging growth without letting inflation get out of hand.

‍

How is the interest rate set?

In the UK, the Monetary Policy Committee (MPC) of the Bank of England meets around eight times a year to review economic conditions and vote on the base rate. They consider:

  • Inflation (measured by CPI)
  • Employment data
  • Economic growth (GDP)
  • Global market conditions

The rate they set affects everything from mortgage repayments to business investment decisions. 

‍

What happens to markets when interest rates rise?

Higher interest rates usually have a cooling effect on the stock market. This can include:

  • Increased cost of borrowing, which can reduce company profits and consumer spending.
  • Growth stocks, especially in tech or early-stage companies, often fall as future earnings are discounted more heavily. Understand growth investing. 
  • Bond prices typically drop as new bonds offer better yields, making older ones less attractive.

Some sectors, like banks through savings accounts and products, may benefit, but overall, rising rates can signal tighter financial conditions. 

‍

What happens to markets when interest rates fall?

Falling interest rates usually encourage investment and spending. This can include:

  • Companies can borrow more cheaply to grow operations.
  • Consumers may spend more as loans and mortgages become affordable.
  • Stocks often rise, especially in growth-focused industries.

Lower rates tend to push investors to seek better returns in the stock market as savings accounts offer low interest rates. 

‍

How can investors adapt to interest rate changes?

Adapting to interest rate shifts is key to managing risk and opportunity when it comes to investing. Some steps investors can typically take are:

  • Diversify across various asset classes to reduce sensitivity to rate movements.
  • Research and consider dividend-paying stocks or defensive sectors (sectors that typically provide essential goods and services that consumers will continue to purchase regardless of the economic climate) during periods of high rates.
  • When rates fall, growth stocks and longer-duration bonds may offer better returns.
  • Review your investment time horizon: short-term savers may prefer fixed-income products, whilst long-term investors could ride out market cycles and potential, although overall investing is for the medium to long term (5 - 10 years+). 

Being aware of how monetary policy affects asset prices can help investors stay aligned with their goals. 

‍

Interest rates and investing impact summary

Interest rates are a powerful economic lever that directly and indirectly shape the investment landscape.

For new investors, understanding their effects is a crucial building block for making smart, informed decisions. Learn about investing basics here. 

Next up: learn how stock markets tend to behave during a recession, and what that means for investors. 

Fintech & the future of investing
2 min read
Expert
Investing trends

What is Fintech?

Fintech, short for "financial technology", refers to the innovative use of technology to deliver financial services in faster, more efficient, and user-friendly ways. 

Whether it's making a payment through your smartphone, automating savings, or accessing investment platforms online, fintech is reshaping how people interact with money.

Its rapid growth has significantly influenced personal finance, banking, and investing, particularly for beginner investors.

‍

How fintech has changed the landscape

Technology has disrupted traditional finance models in a number of ways:

  • Open Banking: This allows licensed fintech firms to securely access financial data (with user permission) from major banks. It encourages competition and enables tailored tools for budgeting, saving, and investing.
  • Cryptocurrencies: Although high-risk and highly volatile, crypto assets have become part of the broader investing conversation, particularly among younger investors.
  • Robo-Advisors: These algorithm-driven tools automate investment decisions based on a user’s goals, risk appetite, and time horizon, reducing the need for human financial advisors.
  • AI and Data Analytics: Artificial intelligence is powering smarter tools for portfolio management, financial planning, and fraud detection. It's also enabling more personalised investment recommendations at scale.
  • Fractional Shares: Enabled by tech platforms, fractional shares allow users to invest in portions of high-priced assets — making investing more affordable and inclusive.

‍

Are fintech companies making investing more accessible?

Fintech companies have had a huge impact on the world of investing. Previously, the entry into investing was a lot higher and more complicated. Fintechs have changed this, such as:

  • Lower Barriers to Entry: Features like fractional shares allow users to start investing with just a few pounds, without needing to buy whole stocks.
  • User-Friendly Interfaces: Many platforms are designed for beginners, offering clear explanations, educational content, and intuitive dashboards.
  • Low/No Minimum Balances: Traditional investing sometimes requires large upfront deposits. Fintech platforms often remove or reduce these requirements.
  • Mobile Access: The ability to manage investments from a smartphone increases access for users who may not live near a traditional financial institution.

‍

Fintech and the future of banking

Fintech isn't just a supplement to traditional banking, it's increasingly becoming an alternative. As digital-native generations demand faster, personalised services, banks are being challenged to innovate or collaborate with fintech providers.

Expect continued growth in features like:

  • Seamless investing integrated within digital banking apps
  • Predictive financial planning using AI
  • More flexible, modular financial products

‍

How are fintechs funded?

Fintech companies often rely on a mix of:

  • Venture Capital (VC): Private investors backing early-stage innovation
  • Crowdfunding: Where everyday users can invest in the company itself
  • Revenue-Based Models: Fees from premium features, subscriptions, or commissions
  • Institutional Investment: From traditional financial players seeking digital exposure

The funding model can impact how a platform grows and the types of services it prioritises.

‍

Do people trust fintech over high street banks?

Consumer trust in fintech is growing, particularly among younger users. While traditional banks benefit from longstanding reputations, fintech platforms offer speed, innovation, and often better user experiences.

However, trust varies depending on:

  • Security protocols
  • Transparency in pricing
  • Customer service quality
  • Regulatory compliance

Surveys show that while many users are open to fintech solutions, trust often increases once users try the service and experience its benefits.

‍

How are fintech companies regulated?

In the UK, fintech companies must be authorised and regulated by the Financial Conduct Authority (FCA). This includes:

  • Ensuring platforms act in the best interests of customers
  • Meeting capital requirements to remain solvent
  • Protecting user data and funds
  • Operating with transparency and fairness

Users can check the FCA Register to verify if a company is properly authorised. Regulation is especially important in protecting users in cases of fraud, poor financial advice, or platform failure.

‍

Fintech summary

Fintech is reshaping the way people in the UK approach investing. From fractional shares to automated tools, it’s lowering barriers and offering more people a path toward building wealth. 

However, it's important to understand how these platforms are regulated, funded, and trusted before diving in.

At the start of your investing journey, you’ll need to decide if you want to take an active or passive approach to your investments.

In the next guide in this Investment Strategies series, we’ll cover the difference between these two strategies.

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.