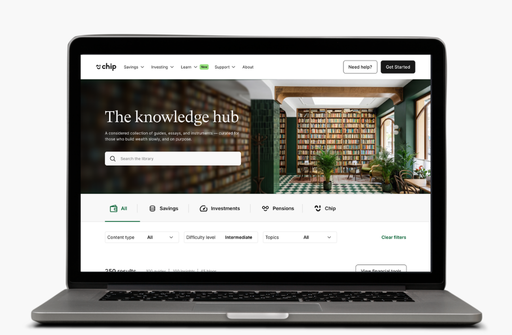
The knowledge hub

A considered collection of guides, essays, and instruments — curated for those who build wealth slowly, and on purpose.

0
results
Filter results
Filter by:
Content type
Difficulty level
Topics
0
results
View financial tools
Understanding investment fees and costs
2 min read
Intermediate
Investing basics

Why investment fees matter

Investment fees can have a significant impact on your portfolio over time. Where you invest, how you invest, how frequently you invest – these can all impact the annual costs of your investments.

If your portfolio earns a 7% average annual return, and your fees add up to 1%, your real returns are only 6%. 

‍

How investment fees affect your returns

It’s easy to shrug off small percentages, as they may not feel like much. This can really add up over a long-term investment horizon, and consider that compounding works in the opposite direction too.

Lets say you invested £100,000 over a 30 year period, with a 7% average return (before fees):

  • 0.25% fees – £761,000
  • 1.5% fees – £574,000

By saving on fees, you’d end up with an extra £187,000!

‍

Types of investment fees explained

If you’re using an investment platform such as Chip, the fees you’ll need to be aware of are platform fees, and fund management fees. 

If you’re using a financial advisor, there will be a fee associated with this. 

In some cases, there are direct fees associated with buying and selling assets. This is more common with trading stocks, mutual funds, and foreign investments; and are typically charged per transaction.

‍

Platform or account fees

Platform fees, sometimes called account fees, are charged by your platform operator to cover certain operating costs.

These fees are usually expressed as a percentage of your portfolio value e.g. with Chip, it’s 0.25% on our free investing plan, or 0% with ChipX*. Some providers charge a flat monthly or annual fee e.g. £4.99 per month. 

Historically, DIY investing was dominated by a few providers, who were able to charge higher maintenance fees.

The development of investment platforms, like Chip, give investors an easily accessible experience at much lower costs. 

*A monthly or annual ChipX membership fee is required and fund management charges apply.

‍

Management fees (OCF)

A management fee, or Ongoing Charge Figure (OCF), represents the annual cost of running a particular investment.

Typically these are applied to investments in ETFs and Mutual Funds. These fees are also expressed as a percentage of your portfolio e.g. 0.45%.

Management fees enable the professionals choosing and managing investments on your behalf, while also researching, trading, and monitoring your investments, to work towards getting you the strongest performance.

If you invest using a ready-made solution, sometimes the platform fee and management fee are layered into one, easy to understand fee. 

For example, if you invested in a ready-made fund with an OCF of 0.45%, using a platform that charged a 0.25% platform fee, you may see this expressed as one fee of 0.7%.

‍

Advisory fees

If you use a financial advisor, or advisory platform, there will be an associated fee, on top of your platform and management fees.

This may be expressed as a percentage of your portfolio, or as a flat fee annual, monthly or even hourly fee for services and consultations. 

Robo-advisors are a relatively new form of advice, and generally come at a lower cost to traditional financial advisors. These can be a separate service, or in some cases are built into platforms themselves. 

‍

Trading or transaction fees

Trading or transaction fees are charged when you buy or sell investments. These are more common with individual stocks, mutual funds, or when investing in assets outside of the UK. 

Some platforms offer commission-free trading, while others may charge a fixed fee per trade (e.g. £5–£10), especially for less frequently traded assets.

It’s worth checking whether your platform charges per transaction or offers commission-free investing.

Over time, frequent trading can rack up costs and eat into your returns, particularly if you're making small trades or investing regularly.

‍

Potentially hidden fees

Inactivity fees

Some platforms may charge a fee if your account is inactive for a certain period—meaning you haven't made a trade or deposit in a while.

While this is becoming less common with modern platforms, it’s worth checking the small print to avoid any surprises.

Foreign Exchange (FX) fees

If you’re investing in international assets (like US stocks or global ETFs), your pounds need to be converted into a foreign currency.

FX fees are usually charged as a percentage of the amount converted – often around 0.5% – 1.5%.

This can apply both when you buy and sell, so it’s important to factor these costs into your decision to invest internationally.

Exit or withdrawal fees

Some providers may charge you for withdrawing or transferring your money out of a platform – particularly when closing an account or moving investments to another provider.

These can be fixed fees (e.g. £25 per fund) or a percentage of your balance. 

Checking exit terms ahead of time can save you from unnecessary costs later on.

Bid-ask spreads

This is the difference between the price a buyer is willing to pay (the bid) and the price a seller wants to receive (the ask).

While this isn’t a “fee” in the traditional sense, it can represent a hidden cost – especially with less liquid investments like certain ETFs or niche funds. 

The wider the spread, the more you might lose when entering or exiting a position. 

‍

How to check the fees you’re paying

Most UK investment platforms (like Chip) provide:

  • A "fees" or "charges" section on the product/fund page

  • A key facts document (KID or KIID) – this is required for each investment fund or ETF

  • Your account summary or statements – often shows what fees you've paid

‍

Understanding retirement and long term investing

Getting yourself on track to a healthy retirement will require some planning, and a long-term investment outlook. Saving simply isn’t enough once you factor in the effects of inflation on a cash sum. 

The next guide will take you through why long-term investing matters, your investment options for retirement, and some planning considerations to keep you on track. 
‍

What are cryptocurrencies and how do they work?
2 min read
Expert
Asset classes

How does cryptocurrency work?

Cryptocurrencies use a technology called blockchain. Think of it like a digital record book (ledger) of every transaction

Instead of this information being stored in one place, like a bank, it’s shared across thousands of computers across the world. 

When you send or receive cryptocurrency, your transaction is added to a ‘block’ of data. Before it’s accepted, it has to be verified by the network in one of two ways:

  • Miners (used in bitcoin) do this by using powerful computer hardware to solve complex puzzles. Solving these puzzles validates a ‘block’ of transactions, adding it to the blockchain, and generating a fixed amount of new cryptocurrency as a reward. Miners are constantly competing to solve these puzzles. 
  • Validators (used in newer systems like Ethereum 2.0) ‘stake’ (lock away) some of their own cryptocurrency, and the network selects a validator at random to check and approve a block of transactions. If they do this honestly, the block is added to the blockchain, and the validator earns a reward – either in the form of transaction fees or newly issued cryptocurrency. 

‍

Why has cryptocurrency become popular?

Cryptocurrency has captured global attention for a number of reasons:

  • Decentralisation and independence from banks and government means no single person or institution is in charge. This appeals to those who want more control over their money. 
  • Volatility has fuelled speculation with prices swinging sharply both up and down, attracting those hoping to profit from big movements. 
  • Blockchain innovation and technology has opened the door to powerful new ideas such as Web3 – giving users ownership of digital services, and NFTs (non-fungible tokens) – digital collectibles with unique ownership. 

‍

Is cryptocurrency a long-term asset?

There are arguments to support the idea that cryptocurrencies have value as a long-term asset, as well as scepticism around cryptocurrency’s short-term ‘hype’ potential:

Long-term value argument:
  • Growing institutional adoption of cryptocurrencies in balanced portfolios by large traditional financial institutions such as BlackRock, Fidelity, and Morgan Stanley. Typical allocations range from 1-3%.1
  • The store-of-value narrative has gained traction during periods of economic uncertainty, as investors look for a hedge against inflation and ways to store value independently of banks or governments.
  • Financial innovation has benefitted from the development of blockchain technology and its role in the evolution of smart contracts (automatic financial agreements removing the need for banks or lawyers), Web3 (the broader movement to a decentralised internet). 

Short-term ‘hype’ argument:

  • Speculative bubbles and herding trends have been identified as a driving force behind some retail investors’ adoption of cryptocurrencies, often triggered by social media noise.2
  • Regulatory concerns have arisen surrounding consumer protection, money laundering and financial stability as infrastructure and regulation remain underdeveloped. 

1Sygnum

2Journal of Financial Innovation

‍

Common risks of cryptocurrency 

Like any investment, cryptocurrencies comes with its own risks, some of which are unique:

  1. Extreme volatility – Price swings can be very turbulent and very reactive to the news cycle. For example, in May 2021, Bitcoin fell around 31% in a single day in response to regulatory concerns and influential social media activity.3 
  2. Regulatory uncertainty – Many countries are still figuring out how to regulate cryptocurrency. Some countries have embraced it and others have imposed strong restrictions or even bans. These regulations can have an impact on prices, purchasing, and the operating capabilities of platforms. 
  3. Security threats – As cryptocurrency is a digital currency, it is open to issues around hacking, scams and theft. Unlike deposits with regulated UK financial institutions, cryptocurrency deposits are not protected by the UK’s Financial Services Compensation Scheme (protects your money up to £85,000 if an institution goes out of business). 
  4. Emotional Investing – Cryptocurrency prices are strongly influenced by investors’ emotions, and those emotions, in turn, are closely tied to price movements.4 

3The Guardian

4Journal of Behavioral and Experimental Finance

‍

What is staking, mining, wallets and crypto ETFs?

If you were investing directly into cryptocurrencies, there are a few technical terms worth getting familiar with, to understand how crypto networks operate and how coins are stored and earned:

  • Staking – The process of locking away some cryptocurrency to support the crypto network. In exchange, it’s possible to earn rewards. This process is used by coins running on a Proof of Stake (PoS) System such as Ethereum, Solana and Cardano. 
  • Mining – The process of solving complex mathematical puzzles using specialised hardware, to verify transactions. Miners can be rewarded with newly created coins and transaction fees. Whilst this process is crucial to the workings of Bitcoin (currently the largest crypto by market cap), the mining process isn’t practical for most investors due to the infrastructure required. 
  • Wallets – After purchasing cryptocurrency, investors usually use a digital wallet as storage. Hot wallets connect to the internet and are more convenient for quicker transactions. However, they’re also more vulnerable to online hacks and scams. Cold wallets are offline storage options such as hardware, which offer more secure storage as they aren’t connected to the internet. These wallets can be more difficult to use and keep safe. 
  • Crypto ETFs – A regulated investment fund traded on a stock exchange that gives investors exposure to the cryptocurrency market, without needing to buy, store, or manage digital assets directly. Some ETFs track the price of crypto assets, and others invest in companies that operate in the crypto and blockchain ecosystem. 

‍

The role of crypto in a diversified portfolio

Cryptocurrency is increasingly being considered by some investors as a way to bring added variety to a wider investment portfolio.

Because crypto assets often behave differently to traditional markets, they may offer:

  • Diversification benefits – their performance may not always move in line with stocks, bonds, or other mainstream assets.
  • Potential inflation hedging – certain cryptocurrencies, such as Bitcoin, are sometimes described as digital stores of value, though this remains debated and unproven over longer timeframes.

That said, it’s important to understand the nature of crypto as an asset class:

  • It’s highly volatile, with prices that can rise or fall sharply in short periods.
  • It’s generally considered a higher-risk investment, and may not be suitable for all investors.
  • Crypto exposure through an ETF can provide a simplified route for accessing the sector, without needing to manage digital wallets or private keys.

‍

Investing in cryptocurrencies summary

Cryptocurrency is a speculative and fast-moving asset class that’s drawn interest for its technological innovation and potential to behave differently from traditional investments. While it is prone to sharp price swings, it may offer diversification benefits when used cautiously.

Whether crypto has a place in your portfolio depends entirely on your goals, risk tolerance, and time horizon.

For experienced investors, a small, controlled allocation may help introduce exposure without taking on the full risks of direct ownership.

‍

FAQs

What is a crypto ETF?

A crypto ETF (Exchange-Traded Fund) is a type of investment fund that provides exposure to the cryptocurrency market without requiring you to buy and store digital assets directly.

Instead, it tracks the price of one or more cryptocurrencies (like Bitcoin), or the performance of companies involved in the crypto ecosystem such as blockchain developers or mining firms.

Like other ETFs, crypto ETFs are traded on traditional stock exchanges and can be bought and sold through investment platforms.

Is it safe to invest in crypto via an ETF?

Crypto ETFs are considered a more regulated and accessible way to gain exposure to the crypto market.

They don’t require managing wallets, private keys, or navigating crypto exchanges which can introduce technical or security risks.

However, they still carry investment risk. The value of a crypto ETF will rise or fall based on the performance of the underlying assets, which can be highly volatile.

So while they simplify the process, the investment itself remains speculative.

Can I invest in Bitcoin through an ETF?

Yes. Some crypto ETFs are designed to track the price of Bitcoin specifically. These ETFs either hold Bitcoin directly (a ‘physical’ or ‘spot’ ETF) or track futures contracts based on Bitcoin prices.

This allows you to gain exposure to Bitcoin’s performance without needing to own or store the asset yourself.

What’s the difference between buying crypto and investing in a crypto ETF?

Buying crypto directly means purchasing digital coins (like Bitcoin or Ethereum) via a crypto exchange. You’ll need a digital wallet to store them securely, and you’re responsible for managing keys, transactions, and safety.

A crypto ETF, by contrast, is a stock market investment. You don’t own the crypto itself, you own shares in a fund that tracks crypto prices or related businesses.

This removes some of the complexity and security concerns, while still giving you access to crypto market movements.

Is crypto a good investment for beginners?

Crypto is a high-risk, speculative asset class. Prices can swing sharply in either direction, and the market is still evolving with regulatory, technological, and security risks to consider.

That said, some investors choose to include a small allocation to crypto as part of a diversified long-term portfolio. If you’re new to investing, it’s important to understand the risks and not invest more than you’re prepared to lose.

ETFs can offer a simpler way to access crypto exposure without needing to manage digital wallets or exchanges directly.

What is asset allocation and why is it important?
2 min read
Intermediate
Portfolio building

What is asset allocation?

Asset allocation is how you divide your investments between different asset types like stocks, bonds, property, and cash, to help achieve your financial goals. 

Each asset type behaves differently, and the right mix can help balance growth potential with risk.

‍

Why is asset allocation important?

Asset allocation is important to ensure your investments match your goals and risk tolerance. Rather than randomly picking investments, it’s about choosing the right balance of assets to suit you.

Different assets respond differently to market conditions. For example, when stocks fall, bonds might hold steady or even rise. By blending asset classes, you reduce the impact of any single investment performing badly.

Without asset allocation, your portfolio could end up being too risky (or too cautious) without you realising it. A deliberate mix helps keep you on track towards your goals while managing the bumps along the way.

See our full guide on risk, returns, and investment strategies.

‍

Maximising return whilst minimising risk

Every investor wants good returns, but chasing the highest potential gains often means taking on more risk. Asset allocation helps you find the sweet spot between risk and reward that works for you.

For example:

  • Stocks tend to have higher long-term returns but more short-term volatility.
  • Bonds generally offer lower, steadier returns and act as a stabiliser during downturns.
  • Cash equivalents are the safest, but have minimal growth potential.

By combining these assets in the right proportions for your goals, you can aim for growth while potentially cushioning against big losses. If you need the money in the short term, you might lean towards safer assets; if you’re investing for decades, you could afford to take more risk for potentially higher returns.

See our full guide on investment types and asset classes.

‍

Conservative portfolio vs aggressive portfolio

Two investors can have completely different asset allocations depending on their risk tolerance and objectives. For example:

  • Conservative portfolio: Might hold 70% bonds, 20% stocks, 10% cash. Lower volatility, smaller potential gains, more focus on preserving capital.
  • Aggressive portfolio: Could be 80% stocks, 15% bonds, 5% cash. Higher volatility, greater potential returns over the long term, more tolerance for short-term dips.

Your portfolio can sit anywhere along this spectrum, and it can evolve as your circumstances change.

See our full guide on defensive and aggressive investing.

‍

What is age-based asset allocation?

Age-based asset allocation is a simple strategy that adjusts your mix of assets as you get older. The idea is to keep a higher risk profile when you’re younger and gradually reduce it as you near your financial goals. 

A common rule of thumb suggests subtracting your age from 100 or 120 to find the percentage of your portfolio to invest in stocks.1 For example:

  • If you’re 30: 100 − 30 = 70% stocks, with the rest in bonds and cash.
  • If you’re 60: 100 − 60 = 40% stocks, with a larger portion in lower-risk assets.

It’s not a one-size-fits-all formula, but it’s a useful starting point for thinking about how risk profiles might change over time.

See our full guide on retirement and long-term investing. 

1Morningstar

‍

How to rebalance your portfolio

Over time, market movements can shift your asset allocation away from your original target. For example, if stocks perform well, they might make up a larger share of your portfolio than planned, which could mean more risk than you intended.

Rebalancing means selling some of the assets that have grown too much and buying more of the ones that have lagged, to restore your desired allocation. Many investors review and rebalance their portfolios once or twice a year.

Making small, purposeful changes can help to keep you moving towards your goal.

‍

Asset allocation summary

Asset allocation is the foundation of a sound investing strategy, helping you balance risk and reward through the right mix of asset classes. Your allocation should reflect your goals, risk tolerance, and time horizon, and it’s worth adjusting it as your life and the markets change.

Next in this series: The importance of diversification, how spreading your investments further within asset classes can strengthen your portfolio.

Investment Types & Asset Classes
2 min read
Intermediate
Investing basics

What are stocks and how do they work?

Stocks (not directly available with Chip), often referred to as shares or equities – are a share of a particular company, issued by a company, on a stock market, in order to raise capital or a market valuation. 

If you purchase a company’s stock, this represents partial ownership in the business. The value of this stock, like any investment, can move up or down. 

If the value goes up, you can sell your shares for a profit, or the company can pay back the increased valuation as a ‘dividend’, a cash payment to investors.

‍

What are bonds and how do they work?

Corporate Bonds, Fixed Interest Securities and Gilts (not directly available with Chip) are loans that you pay to a company, or government, and they agree to pay you back, with interest, after a fixed time period. 

The returns you earn are fixed, and are usually made in regular interest payments, if you own the bond directly. They offer greater stability to a portfolio, as they are less volatile than owning stocks, where the value can dramatically go up or down. 

The downside risk to bonds is that if interest rates go up, the value of the bond will decrease, because newly issued bonds with better returns become more attractive to investors. 

If they run into financial difficulty, there is a small risk that a company or government is unable to pay you back, but this is more associated with lower quality, or ‘junk’ bonds. So do your research carefully. 

‍

What are ETFs and how do they work?

Exchange-traded funds (ETFs) are collections of assets that can be bought and sold on a stock exchange. They can hold a variety of different asset classes, from company equities to commodities, bonds and currencies – under one variable market value. 

ETFs can track everything from a varied market index, to a specific commodity or thematic. Each fund comes with its own risk profile, and it's always important to consider the holdings when selecting your investments. Learn about ethical and thematic investing.

‍

What’s the difference between stocks, bonds and ETFs?

Stocks give you ownership in a single company. They can deliver high returns, but they also carry more risk – if that company underperforms, your investment might lose value.

Bonds are loans to companies or governments. They usually offer lower, more stable returns and are less volatile, but they’re not immune to risk, especially if inflation or interest rates rise.

ETFs, on the other hand, are a way to invest in lots of stocks (or bonds) at once. Think of them as a shortcut to diversification – helping you reduce risk while still aiming for solid long-term returns. They combine the trading flexibility of stocks with the diversification benefits of a fund.

‍

What is an index fund and how does it work?

Index funds passively track the price of a specific market index, automatically investing in all the companies within it. This provides broad market exposure rather than focusing solely on top-performing stocks. 

A stock market index is simply a representation of the performance of a particular section of the market. Understand stock market basics here.

You may have heard of names like the FTSE 100 for the UK market, the S&P 500 in the US, and the Nikkei 225 in Japan. For example, the FTSE 100 index represents the performance of a grouping of the 100 largest companies in the UK by value. 

As the market prices of the indexed companies move, so does the overall price of the index. Investors tend to use these indices as a benchmark, for the overall performance of a particular market.

These indexes are then tracked by fund managers, in an index fund. This facilitates investment into these top performing companies. 

‍

What are commodities and how do they work?

Commodities (not directly available with Chip) are physical goods that can be bought or sold – typically raw materials or natural resources. Think gold, silver, oil, coffee, wheat… even livestock. 

These goods are traded on commodity markets – rather than a stock market – where their prices are driven by global supply and demand. For example, if there’s a drought affecting wheat crops, wheat prices might go up. If oil supply increases, prices might fall.

There are two main ways investors can access commodities:

  • Directly – by buying the physical asset, like a gold bar (though – let’s face it – this can be impractical for most people).
  • Indirectly – through ETFs, ETCs (Exchange Traded Commodities — structured as debt security), funds or shares in companies that produce the commodity (like oil companies or mining firms).

‍

What are cryptocurrencies and how do they work?

Cryptocurrencies (not directly available with Chip) are digital currencies that operate independently of central banks or governments. The most well-known is Bitcoin, but there are thousands of others, like Ethereum and Solana.

They work using a technology called blockchain: a secure, decentralised digital ledger that records all transactions. This makes crypto hard to counterfeit and, in theory, more transparent.

You can invest in cryptocurrency by:

  • Buying coins or tokens directly via crypto exchanges.
  • Investing in crypto funds or companies involved in blockchain technology.

Crypto markets are known for being highly volatile – prices can rise or fall quickly, often influenced by news, regulation changes, or market sentiment. While some see crypto as a long-term investment or a future form of money, others view it as extremely speculative and high risk.

Because of this, it's important to approach cryptocurrency with caution and only invest what you're prepared to lose. Learn about investing risks.

‍

What is diversification & why does it matter?

Diversification is a fancy word for ‘not putting all your eggs in one basket’. It’s a way of managing risk by spreading your investments across different types of assets, sectors, or even countries.

Why is it important? Because not all investments move in the same direction at the same time. When one part of your portfolio dips, another might rise. Diversifying helps to smooth out your overall returns over time.

For example, if stocks are struggling but bonds are holding steady, a diversified portfolio will usually perform better than one with just stocks. It’s all about balance, and protecting yourself from the unexpected. Learn about managing your investment portfolio.

‍

Understanding risks, returns and investment strategies

All investing involves some level of risk – that’s what sets it apart from saving. But understanding the relationship between risk and return helps you make better decisions for your goals and investing timeline.

The next guide in our series takes a look at understanding risk, calculating returns, and different investing strategies in more detail. 

‍

Direct investment into individual stocks, bonds and cryptocurrencies are not available via the Chip platform. Chip offers investment funds that invest in different assets as a collective investment.

‍

What is diversification?
2 min read
Beginner
Portfolio building

Understanding the importance of diversification

Markets can move unpredictably. One asset class might be soaring while another is falling. Diversification ensures you’re not overly reliant on a single investment or sector to meet your financial goals.

For example, if your portfolio is made up entirely of tech stocks, a downturn in the tech industry could cause a sharp drop in your portfolio. But if you also own bonds, commodities, and shares in other industries, those assets may hold steady or even rise, helping cushion the blow.

Diversification doesn’t guarantee profits, but it can make the investing journey less bumpy by balancing the ups and downs.

‍

Diversification strategies in investing

There are many ways to diversify a portfolio. Investors often combine several of the following approaches:

  • Asset classes: such as stocks, bonds, real estate, commodities, or cash equivalents.
  • Industries and sectors: spreading across technology, healthcare, finance, consumer goods, and more.
  • Market capitalisations: investing in both large, stable companies (blue chips) and smaller, growth-focused firms.
  • Risk profiles: mixing higher-risk, higher-return assets with safer, lower-yield options.
  • Tangibility: balancing between traditional financial assets and physical assets like property or gold.

The right mix depends on your goals, time horizon, and risk tolerance.

‍

Advantages of diversification

  • Could reduce the risk of heavy losses from one sector.
  • Could provide protection against market fluctuations.
  • Could help investors achieve steadier long-term growth. 
  • Offers exposure to different markets and opportunities. 

‍

Disadvantages of diversification
  • Can limit short-term gains if one area performs very well.
  • More complex and time-consuming to manage.
  • May involve higher costs or fees, especially if spread out across platforms. 
  • Can feel overwhelming for new investors looking for a simpler approach. 

‍

How to assess portfolio diversification

Holding several different investments doesn’t guarantee your portfolio is diverse, the weighting of each investment matters too.

For example, holding ten different stocks might look diverse, but if they’re all in the same industry, you’re still exposed to the same risks.

One way to assess diversification is by looking at how much of your portfolio is concentrated in one asset class, sector, or company. Tools and portfolio trackers can help you see where your money is spread and identify any gaps or imbalances.

See our full guide on portfolio management.

‍

Diversification summary

Diversification is one of the simplest yet most effective ways to manage risk in investing. By spreading your money across different asset types, industries, and markets, you can give yourself a smoother journey towards your long-term goals.

Next in this series: How to rebalance your portfolio, why it matters and how to adjust your investments to stay on track.

5 Easy Ways To Help Save Money
2 min read
Beginner
Savings Strategies & Tips

There are many simple and effective ways to cut down on your spending, so you can save more money each month. 

If you're looking for some inspiration on how to save money in the UK, here are five great tips to help you get started. See how long it will take to reach your savings goal with our savings calculator.

‍

1) Make a budget and stick to it

The first and most important step to saving money is to have a budget. A budget is simply a plan for your money, which helps you see exactly where your money is going.

Make a list of all your income and expenses, and see where you can cut down. 

Once you have a savings budget, make sure you stick to it. This is the key to saving money and keeping your finances under control. Learn about different savings accounts.

This is not financial advice - this is about simple tips to get going, while not impacting your day to day life or living a life of extreme frugality.

So if this sounds like it’s for you, read on!The following should not be taken as advice or guidance around financial hardship. If you're in this situation, there is support available from GOV.UK or Citizens Advice that can help.

‍

2) Cut down on your food expenses

Food is one of the biggest expenses in many households. By being smart about your food shopping, you can save a lot of money. 

For example, buy food in bulk when it is on sale, and freeze it for later. Consider swapping big brands for own brand products or using discount supermarkets.

Cook meals at home instead of eating out, and bring your lunch to work instead of buying it. These small changes can add up to big savings.

‍

3) Reduce your energy bills

Another way to save money is by reducing your energy bills. You can do this by washing your clothes at 30 degrees, using energy-efficient light bulbs, and turning off appliances when they're not in use.

Heating is a big expense so turning down radiators and the flow temperature of your boiler to 60 degrees can also help you make big savings over the year. 

There are plenty of resources online such as GOV.UK with tips.

‍

4) Shop around for the best deals

When it comes to buying things like insurance, broadband, and mobile phone contracts, it's important to shop around for the best deals. 

Don't just go with the first offer you see, take the time to compare prices and find the best deal for you. You can use price comparison websites to make this easier.

‍

5) Save a little each month

Finally, one of the easiest ways to save money is by setting aside a little each month. You don't have to save a lot, just a few pounds here and there.

Start by setting up a regular amount (on payday for example) to go from your bank account to a savings account and watch your savings grow over time.

Saving money is all about being smart with your finances. By following these five money-saving tips, you'll be able to cut down on your spending and keep more money in your pocket. So, why not get started today?

Mark Zuckerberg unveils AI ‘charm’ device that can fit on a keychain

2 min read

Mark Zuckerberg said Meta’s new personal AI agent Muse has become the “centrepiece” of his AI vision, as he unveiled a new handheld AI “charm” device that will feature the interactive assistant.The Meta chief used the company’s annual Connect event at its Silicon Valley headquarters to announce Muse Charm, a small pendant-like device that fits on a keychain and is activated by a fingerprint sensor.

The device, which features a screen showing the Muse avatar, will also have real-time voice interactivity and is set to be released in December.

“If you’re not wearing glasses, this is going to be by far the fastest way to talk to your Muse and to show what’s going on around you,” the chief executive said.

Muse, development of which was first revealed by the FT in May, has helped change the momentum of Zuckerberg’s huge bet on AI, quickly becoming the most downloaded app on both the Apple and Android app stores in the US since its launch two weeks ago.

The easy-to-use app offers consumers a team of autonomous bots to carry out everyday tasks, such as ordering groceries, booking travel and organising finances.
‍

Meta's Mark Zuckerberg announces Muse Charm © AP Photo/Jeff Chiu

‍

Zuckerberg on Wednesday also announced new capabilities for Muse, including the ability to have live conversations with the interactive AI assistant, and insisted that it has “state-of-the-art privacy and security”.

The Meta founder has come under increasing pressure from Wall Street as he pours billions of dollars into AI infrastructure and talent, with Meta’s share price falling by more than a quarter between last September and the beginning of August.

But Meta’s stock has bounced back since the September 8 launch, adding $300bn to its market capitalisation. The stock was slightly higher in after-hours trading on Wednesday.
‍

Muse Charm is a small pendant-like device that fits on a keychain and is activated by a fingerprint sensor

‍

The release of a breakout product to Meta’s 3bn users caps a turbulent two years in which Zuckerberg has repeatedly struggled to compete with OpenAI and Anthropic in developing frontier AI models and features.

Zuckerberg on Wednesday said he believed Muse would “make users money”. As a result, the company would offer a free Muse tier “with the expectation that over time we will profit by taking a small fee from transactions”.

Whether Zuckerberg will emerge vindicated in the long term in his AI strategy — for both his Muse assistant and AI wearables — will depend on whether the new features can withstand potential privacy and security issues as its user base grows.

The Meta chief has bet that smart glasses and other portable devices will become one of the main ways consumers interact with AI, despite critics dubbing its camera-toting Ray-Bans “pervert glasses” after intrusive videos hit Instagram and TikTok.

AP Photo/Jeff Chiu

‍

Sold in partnership with eyewear group EssilorLuxottica, the glasses have inbuilt speakers, microphones and cameras that can be used to take photos, listen to music and chat with Meta’s AI.

Critics claim they are being used to record others without their knowledge. Currently the Meta glasses have an LED in the corner of the frame that lights up to signal to others when a wearer is taking photographs or filming.

On Wednesday, Zuckerberg announced a pair of Ray-Bans with no camera that customers can interact with using audio only, alongside several new frame styles from Ray-Ban and the cheaper Meta glasses range.

Meta also launched new virtual reality glasses, which will be available next spring for $1,300 and are five times lighter than the previous Quest 3 model.

Meta said the Muse assistant would soon be available on its glasses. Users will also now be able to have a hyper-realistic digital avatar represent them on video calls while they are wearing the glasses since the spectacles cannot film the wearer’s face.

The avatars use hologram technology that Meta has been working on for years.

Meta — so far the only large AI lab to have rolled out a consumer-friendly agentic assistant — hopes Muse will be able to become highly personalised for users if it is able to access data from activity on its social platforms.

But the company will have to convince consumers to connect personal data, such as their email inbox, financial services apps or calendar, with the bots, which run on the social media group’s Muse family of models, at a time when AI agent technology can still make errors or potentially go rogue.

Meta has already had to issue a fix for a vulnerability that could allow a hacker to take control of another person’s Muse agent. Meanwhile, Amazon has blocked Meta’s agents from accessing its shopping platform as part of efforts to prevent third-party bots from using its systems.

‍

‍

Cash ISAs Explained
2 min read
Beginner
Accounts & Products

What is a Cash ISA?

A cash ISA, short for Cash Individual Savings Account, is similar to a conventional savings account. However, its distinctive feature is the exemption from taxation on the interest earned.

In each UK tax year (which runs from April to April), you can deposit up to £20,000 into a cash ISA.

ISA savings are in addition to the Personal Savings Allowance (PSA), which permits basic rate taxpayers to earn up to £1,000 in savings interest annually without incurring tax liabilities.

Higher rate taxpayers (40% tax rate) qualify for a reduced PSA of £500 per year, while additional taxpayers earning £150,001 or more do not receive any allowance.

ISA limits apply. £20k per tax year. Chip does not provide tax advice or financial advice. Tax treatment depends on individual circumstances and may be subject to change in the future.

‍

How do Cash ISAs Work?

If you're thinking about using a cash ISA to grow your savings, here's a brief overview of how they work:

  • Cash ISAs are typically easy to open.
  • You can save up to £20,000 annually, and your account accrues interest similar to a standard savings account.
  • A variety of cash ISAs are available, such as easy access, regular saver, fixed rate, and junior ISAs for individuals under 18.
  • Different ISAs may have varying terms, including withdrawal restrictions on fixed rate cash ISAs.
  • Transferring funds from previous tax years into a higher-yield ISA account is possible. Avoid closing an ISA when switching; instead, contact your new ISA provider to facilitate the transfer.

‍

Interest Rates on Cash ISAs

The interest rate depends on the type of cash ISA and the chosen provider. Fixed rate cash ISAs offer a guaranteed return for a set period, whereas variable rate cash ISAs may change if the provider adjusts its interest rates.

Use our interest rates calculator to see how much you could earn. 

Cash ISA interest rates can vary between financial providers, so it’s always good to do your research with comparing Cash ISA rates.

‍

Cash ISA factors to think about

Before opening a cash ISA, consider the following factors:

1. Interest Rate: The interest rate determines your savings' returns. Be aware that initial high introductory rates may decrease after a year, so consider transferring your ISA funds to a higher-yielding account at that point.

2. Account Type: Choose between easy access, fixed, or regular saver ISAs based on your preferences for return and accessibility.

3. Alternative ISAs: Apart from cash ISAs, you can explore stocks and shares ISAs. These involve investing in the stock market, offering potential rewards but also bearing some level of risk.

4. Annual Limit: You can open only one cash ISA each year. Think carefully before selecting your cash ISA, keeping in mind that your total ISA savings can't exceed £20,000 in any tax year.

5. Deadline: The tax year concludes on April 5th. Any unused ISA allowance cannot be carried over, so invest before this date to maximise your tax-free benefits.

‍

How Many Cash ISAs Can I Have?

You can have multiple ISAs, but you can only deposit a maximum of £20,000 in a given tax year.

Be aware that transferring funds from previous years' ISAs does not count towards this limit.

‍

Cash ISA Rules

Cash ISA rules are straightforward:

  • You can deposit a maximum of £20,000 per tax year.
  • Transfers from existing cash ISAs to new cash ISAs or splitting transfers among different providers are allowed.
  • To switch between cash ISA providers, you must request a transfer. If you withdraw the money yourself, you'll lose your tax-free allowance on the entire sum.
  • You can transfer money from a stocks and shares ISA to a cash ISA, but this requires a form to be submitted to the new provider (but please note you can't currently do this with Chip).

‍

Pros and Cons of Cash ISAs

Pros of cash ISAs:

  • Tax-free savings.
  • No risk of capital loss compared to stocks and shares ISAs.
  • Flexibility to transfer to higher-yield accounts while retaining tax advantages.

Cons of cash ISAs:

  • High interest rates may drop after the first year.
  • Fixed rate cash ISAs may lock your money for a set period.
  • Not all accounts accept transfers from previous years, and exit fees may apply.

‍

Switching Cash ISAs

Switching could be considered if you find an account offering a higher interest rate. Ensure the new provider accepts transfers and inquire about any penalties for moving your funds.

You can transfer savings from both the current and previous years. It may also be possible to request a partial cash ISA transfer however not all providers can facilitate this.

Avoid closing the ISA, as this would result in losing the tax benefits. Instead, contact the new provider to arrange the transfer.

The multi-account strategy: Maximising your savings potential
2 min read
Expert
Accounts & Products

Why use multiple accounts?

Each type of savings account offers different perks. By splitting your money across several accounts, you can:

  • Maximise interest: Some accounts offer better rates for certain types of savings.
  • Keep your money accessible: Different accounts offer varying levels of access to your funds.
  • Meet different savings goals: Whether it’s an emergency fund, retirement savings, or a holiday fund, separate accounts can help keep your financial goals on track.
  • Benefit from tax perks: Some accounts offer tax-free savings, giving you more return on your money.
  • Reduce risk: Spreading your money across different accounts means you’re less exposed to market changes or poor interest rates in one area.

‍

How to leverage UK savings accounts

Now, let’s explore the key UK account types and how to build them into your multi-account strategy:

1. ISAs (Individual Savings Accounts)

ISAs allow you to save up to £20,000 a year tax-free. This makes them an essential part of any savings strategy. Max out your ISA allowance if possible to shield more of your savings from tax. 

2. Instant access accounts

Instant access accounts let you withdraw money whenever you need it. While the interest rates are (generally) lower, the liquidity makes them perfect for short-term goals and emergency funds. Try to keep 3-6 months of living expenses here to cover any unexpected costs.

3. Fixed-term savings accounts

These accounts offer better interest rates if you’re willing to lock your money away for a set period, typically ranging from one to five years. Use fixed-term accounts for medium- to long-term goals, such as buying a house or a big future purchase.

4. Prize-linked accounts

Instead of traditional interest, accounts like the Chip Prize Savings Account offer the chance to win tax-free prizes. Though there’s no guaranteed return, the prospect of winning big can be an exciting addition to your savings.

Prizes are not cash and are applied to your Chip account as a bonus. Prizes become cash once you withdraw your entire Prize Savings Account balance into your linked bank account.

T&Cs, eligibility criteria and minimum average balance of £10 applies. For current prize values, entry and eligibility criteria and how to opt-out see our full terms”.  FSCS limits of £120,000 apply to eligible deposits. Prizes are not eligible for FSCS protection.” (if mentioning the FSCS scheme).

‍

Structure your savings

Here’s how a typical multi-account setup might look:

  • Emergency fund: Instant access account for peace of mind.
  • Short-term goals: Cash ISA or high-interest instant access for a holiday or new car.
  • Medium-term goals: Fixed-term accounts for savings you don’t need immediately.
  • Long-term goals: Stocks & Shares ISA or a Cash ISA for retirement or a future property purchase.
  • “Fun” money: Prize-linked accounts for a chance to win big.

‍

Tailor your strategy

The multi-account strategy is about building a system that works for your unique financial needs. Whether you’re saving for a rainy day, a dream holiday, or retirement, using multiple accounts lets you optimise every pound.

Make sure to review your strategy regularly, keeping up with the latest offers and adjusting your approach as your financial situation evolves. With a tailored multi-account system, you’re not just saving – you’re setting yourself up for financial success.

Note: Chip does not provide financial or tax advice. Tax treatment depends on individual circumstances and may be subject to change in the futureAlways consult a professional for personalised recommendations.

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.